By TradeRiskMath Editorial Team
Your net worth is one of the clearest ways to measure your financial progress. It shows how much you own compared with how much you owe, giving you a snapshot of your financial position at a particular moment.
You do not need to earn a six-figure salary, own a house, or have a large investment portfolio to calculate it. If you have money in a bank account, retirement savings, a car loan, or credit card debt, you already have the information needed to get started.
But here is something important: your net worth can increase even when you are not making meaningful financial progress, and it can decrease even when you are making smart financial decisions.
Imagine a family that saves $500 every month and consistently pays down its debt. Their financial habits are improving, but a stock market decline could temporarily reduce the value of their investments. Their net worth might fall even though they are moving in the right direction.
This guide explains how to calculate your net worth, which assets and debts to include, and how to track your progress over 12 months without confusing investment performance with the results of your financial decisions.
What Is Net Worth?
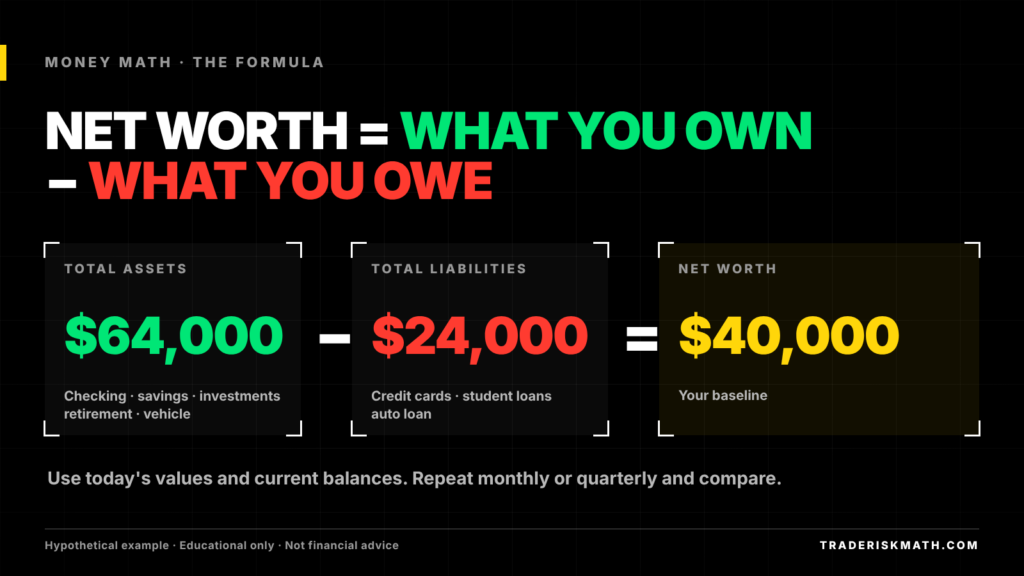
Net worth is the difference between the total value of your assets and the total amount of your liabilities.
In simple terms:
- Assets are things you own that have financial value.
- Liabilities are debts and financial obligations you owe.
- Net worth is what remains after subtracting your liabilities from your assets.
For example, suppose you have $15,000 in savings and investments but owe $6,000 on a car loan and credit cards.
Your net worth is $9,000.
You might not have $9,000 sitting in your bank account. Instead, that number represents the difference between what you own and what you owe.
The Net Worth Formula
Net Worth = Total Assets − Total Liabilities
A positive result means your assets exceed your liabilities. A negative result means you owe more than the value of your assets. Neither number tells your entire financial story, but both provide a useful starting point.
How to Calculate Your Net Worth in 5 Steps
Calculating your net worth is straightforward when you gather your information systematically.
Step 1: List All Your Assets
Start by identifying everything you own that has measurable financial value. Use current balances or reasonable estimates of what your assets are worth today.
Common assets include:
| Asset | What to Include |
|---|---|
| Checking accounts | Current balances across your checking accounts |
| Savings accounts | Emergency funds and other savings |
| Certificates of deposit | Current account value |
| Taxable investments | Stocks, ETFs, mutual funds, bonds, and other investments |
| Retirement accounts | 401(k), traditional IRA, Roth IRA, and similar accounts |
| Real estate | Estimated current market value of your home or other property |
| Vehicles | Estimated resale value of cars, trucks, or motorcycles |
| Other assets | Business ownership, valuable property, or other assets with a reasonable resale value |
Important: Use the value of an asset today, not necessarily what you originally paid for it. A vehicle purchased for $30,000 several years ago may now be worth $15,000.
Avoid inflating your totals with unrealistic estimates. Everyday household items often have little resale value, so you do not need to assign a price to every piece of furniture or appliance.
Step 2: List All Your Liabilities
Next, record the outstanding balances on your debts. Use the amount you currently owe rather than the original loan amount or your monthly payment.
| Liability | What to Include |
|---|---|
| Credit cards | Outstanding balances on all cards |
| Student loans | Remaining federal and private student loan balances |
| Auto loans | Outstanding vehicle loan balances |
| Mortgage | Remaining principal owed on your home loan |
| Personal loans | Outstanding balances on unsecured loans |
| Other debts | Medical debt, lines of credit, and other outstanding obligations |
For example, if your original student loan was $25,000 but you have paid it down to $18,000, record $18,000.
Do not count the same debt twice. If you track several credit cards individually, add their balances once to your liability total.
Step 3: Calculate Your Total Assets
Add every asset you listed in Step 1.
Consider this example:
| Asset | Current Value |
|---|---|
| Checking account | $2,000 |
| Savings account | $8,000 |
| Taxable investments | $12,000 |
| Retirement accounts | $28,000 |
| Vehicle | $14,000 |
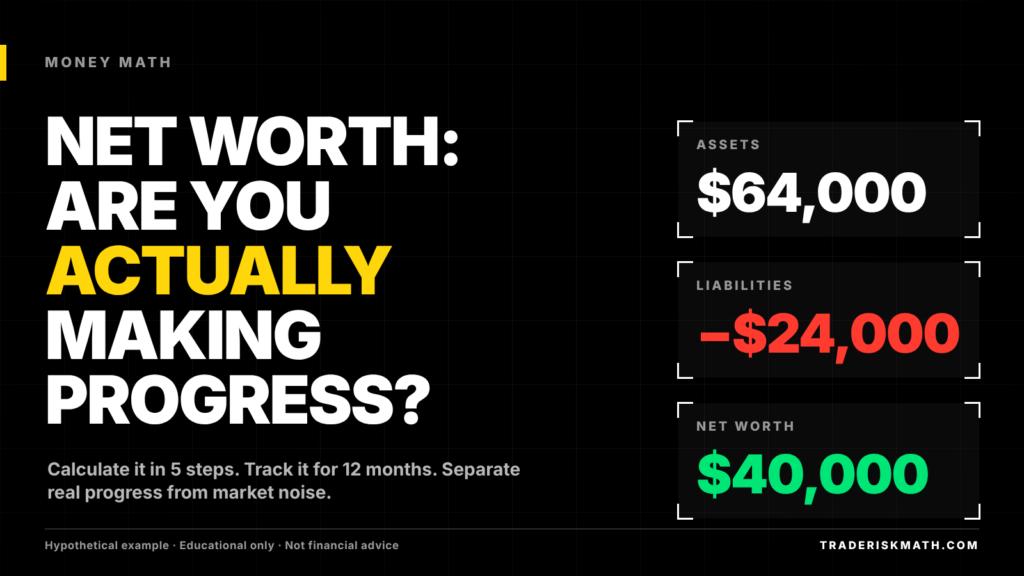
| Total assets | $64,000 |
The total value of these assets is $64,000.
Step 4: Calculate Your Total Liabilities
Now add all outstanding debts.
| Liability | Current Balance |
|---|---|
| Credit cards | $3,000 |
| Student loans | $12,000 |
| Auto loan | $9,000 |
| Mortgage | $0 |
| Total liabilities | $24,000 |
In this example, the person has $24,000 in total liabilities.
Step 5: Subtract Liabilities From Assets
Use the net worth formula:
Total assets: $64,000
Total liabilities: $24,000
Net worth = $64,000 − $24,000 = $40,000
The person’s net worth is $40,000.
This is their financial starting point. To understand whether they are improving, they need to repeat the calculation and compare the results over time.
Calculate Your Net Worth With the TradeRiskMath Calculator
You can perform the calculation yourself using the tables above, or use the TradeRiskMath Net Worth Calculator to organize the numbers and calculate the difference.
Use the TradeRiskMath Net Worth Calculator
Enter your asset values and outstanding liabilities using the fields provided by the calculator. Review the result and save a copy of your totals so you can compare them with future calculations.
Your first calculation establishes your baseline. Repeating it monthly or quarterly helps you see whether your overall financial position is changing.
Note: Make sure the calculator link matches the published URL of the Net Worth Calculator on TradeRiskMath before publishing this article.
What Does Your Net Worth Tell You?
Your net worth can be positive, zero, or negative.
Positive Net Worth
Your assets are worth more than your liabilities.
For example:
- Total assets: $75,000
- Total liabilities: $30,000
- Net worth: $45,000
You have $45,000 more in assets than outstanding liabilities. That does not mean you have $45,000 available to spend, since much of your wealth may be held in retirement accounts, investments, or property.
Zero Net Worth
Your assets and liabilities are equal.
For example, if you own $20,000 in assets and owe $20,000, your net worth is zero.
This is a mathematical snapshot, not a judgment about your financial habits or future prospects.
Negative Net Worth
Your liabilities exceed your assets.
For example:
- Total assets: $12,000
- Total liabilities: $20,000
- Net worth: −$8,000
You owe $8,000 more than the value of your listed assets.
Negative net worth can occur when someone has student loans, recently purchased a vehicle, or is early in their financial journey. The more useful question is whether the gap is narrowing over time.
A 12-Month Example: How One Household Tracks Financial Progress
Let’s follow a fictional household: Maya and Jordan, a couple who want to build savings, invest consistently, and reduce their debt.
At the beginning of the year, they calculate their combined net worth. Instead of focusing only on a final dollar amount, they track the decisions and circumstances that influence it.
Their Starting Financial Position
At the beginning of January, their balance sheet looks like this:
| Category | January Value |
|---|---|
| Checking and savings | $10,000 |
| Taxable investments | $15,000 |
| Retirement accounts | $35,000 |
| Vehicle and other assets | $20,000 |
| Total assets | $80,000 |
| Credit cards | $5,000 |
| Student loans | $15,000 |
| Auto loan | $10,000 |
| Total liabilities | $30,000 |
| Starting net worth | $50,000 |
Their starting net worth is $50,000.
Maya and Jordan establish three goals:
- Add money to savings every month.
- Reduce their credit card and other loan balances.
- Continue contributing to retirement accounts without relying on stock market gains to measure their success.
Their Net Worth Throughout the Year
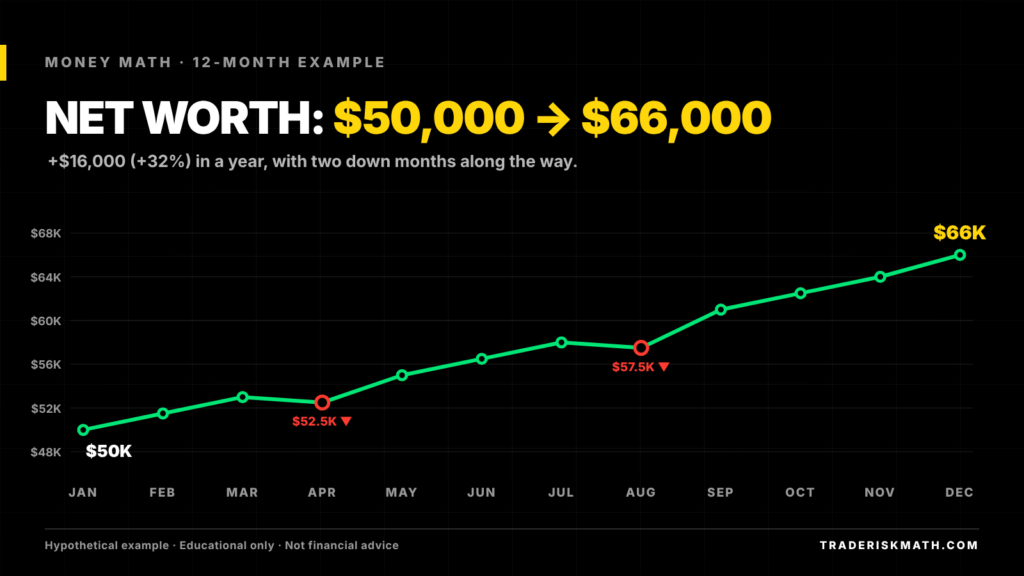
The following table shows one possible 12-month path. These figures are illustrative, not actual household data or a forecast.
| Month | Total Assets | Total Liabilities | Net Worth |
|---|---|---|---|
| January | $80,000 | $30,000 | $50,000 |
| February | $81,000 | $29,500 | $51,500 |
| March | $82,000 | $29,000 | $53,000 |
| April | $81,000 | $28,500 | $52,500 |
| May | $83,000 | $28,000 | $55,000 |
| June | $84,000 | $27,500 | $56,500 |
| July | $85,000 | $27,000 | $58,000 |
| August | $84,000 | $26,500 | $57,500 |
| September | $87,000 | $26,000 | $61,000 |
| October | $88,000 | $25,500 | $62,500 |
| November | $89,000 | $25,000 | $64,000 |
| December | $90,000 | $24,000 | $66,000 |
By December, their net worth has increased from $50,000 to $66,000.
Net worth increase = $66,000 − $50,000 = $16,000
That represents a 32% increase from their starting net worth.
However, the increase alone does not explain how much progress came from saving, debt repayment, investment performance, or changes in the value of their possessions. To understand that, they need to examine what happened during the year.
What Their Numbers Actually Mean
Over the 12 months:
- Their total assets increased by $10,000.
- Their total liabilities decreased by $6,000.
- Their net worth increased by $16,000.
The $16,000 improvement came from the combined effect of changes in their assets and liabilities.
But it would be incorrect to assume that they saved exactly $10,000 or earned $16,000 from investing. Their asset values can change for several reasons, including deposits, withdrawals, market gains and losses, and changes in the resale value of their vehicle.
The next step is to separate those influences.
The Difference Between Real Financial Progress and Market Gains
One of the most common mistakes in net worth tracking is assuming that every increase represents money earned or saved.
Imagine Maya and Jordan’s investments increase in value by $5,000 because the stock market performs well. Their net worth may rise even if they do not save an additional dollar that month.
Now imagine the market declines and their investments lose $4,000 in value. Their net worth could fall even though they continued saving and paying down debt.
Neither result, on its own, tells the whole story.
Four Factors That Can Change Your Net Worth
1. Saving and investing
When you move money from your paycheck into savings or invest it in a brokerage account, you are building financial assets. If the money comes from income that would otherwise have been spent, your net worth can increase.
Moving money from checking to savings alone does not increase net worth; it simply changes where the money is held.
2. Paying down debt
When you pay down a loan using money from your bank account, both your assets and liabilities decrease. The principal portion of the payment generally improves your net worth by reducing what you owe, while interest and fees are costs that do not reduce the principal balance.
For example, paying $500 toward loan principal reduces your liabilities by $500. If that $500 comes from an asset already counted in your net worth, your net worth generally improves by $500, assuming no other changes.
3. Investment gains and losses
Stocks, ETFs, mutual funds, and other investments fluctuate in value. These changes affect your net worth even when you do not buy or sell anything.
Investment gains can contribute to wealth building, but they are uncertain and can reverse. A market-driven increase should not be confused with money deposited from your income.
4. Changes in the value of property
Your home or vehicle may rise or fall in value. If your home increases in estimated market value, your net worth may increase even if you have not made extra mortgage payments.
Likewise, depreciation can reduce the value of your vehicle. These changes matter to your balance sheet, but they are different from the effect of saving or paying down debt.
A Simple Way to Separate the Changes
At the end of each month, ask yourself:
- How much money did I add to savings and investments from income?
- How much principal did I pay off on my debts?
- How much did my investments gain or lose?
- Did the estimated value of my property change?
- Did I withdraw savings, take on new debt, or make a major purchase?
These questions help explain why your net worth changed instead of simply showing whether it went up or down.
For a more precise analysis, track contributions, withdrawals, debt principal reductions, investment returns, and property-value changes separately. Avoid counting the same money twice when it moves between accounts.
How to Track Your Net Worth Every Month
You do not need complicated software to monitor your financial progress. A spreadsheet, notebook, or financial calculator can work.
Follow this simple routine.
1. Choose a Consistent Date
Calculate your net worth on the same date each month, such as the last day of the month.
Using a consistent schedule makes comparisons more meaningful because you are measuring your finances at regular intervals.
2. Record Current Balances
Gather your bank statements, investment account balances, retirement account values, and loan statements.
Use current balances rather than estimates from memory. For investments and property, record the valuation date so you know when the figures were measured.
3. Compare Your Current and Previous Results
Subtract your previous net worth from your current net worth.
Change in Net Worth = Current Net Worth − Previous Net Worth
If last month’s net worth was $50,000 and this month’s is $52,000, your net worth increased by $2,000.
Then investigate what caused the change.
4. Review Your Progress Against Your Goals
A useful review goes beyond the headline number. Look at whether your emergency savings are growing, high-interest debt is shrinking, retirement contributions are continuing, and your spending is consistent with your goals.
A month with a negative investment return may still represent a productive month if you saved consistently and reduced expensive debt.
5. Keep a Record of Every Calculation
Save each month’s asset total, liability total, net worth, and a short note explaining major changes.
Over time, this record can help reveal patterns that are difficult to notice when you look only at your current bank balance.
How Often Should You Calculate Your Net Worth?
For most households, monthly or quarterly tracking is a practical starting point.
Monthly tracking can help you spot changes in spending, debt, or savings. Quarterly tracking may be easier if your financial situation is relatively stable or you prefer less frequent reviews.
Annual calculations can be useful for a broad comparison, but they may make it harder to identify when a financial change occurred.
You do not need to react to every short-term fluctuation. The purpose is to understand your financial direction, not to worry about every movement in the stock market.
Common Net Worth Calculation Mistakes to Avoid
Even a simple calculation can be misleading if the numbers are incomplete or inconsistent.
Forgetting retirement accounts. Include eligible retirement assets, even if you do not plan to access the money for decades. Keep in mind that account values may fluctuate and withdrawals may have tax consequences.
Using the original purchase price of an asset. Use a reasonable estimate of its current value instead of what you paid for it.
Ignoring small debts. A few outstanding balances can add up. Include credit cards, personal loans, and other debts that you owe.
Counting assets twice. If a total already includes several accounts, do not add those accounts again separately.
Confusing income with wealth. A high salary does not automatically produce a high net worth. Spending, saving, borrowing, and investment results also affect the outcome.
Assuming a higher net worth means more spending money. Your net worth may include retirement accounts, home equity, and investments that are not immediately available without costs, restrictions, or market risk.
Comparing your results with someone else’s without context. Age, household size, income, location, debt, and time spent building assets all affect financial circumstances. Your own progress toward realistic goals is often a more useful benchmark.
What If Your Net Worth Is Negative?
A negative net worth does not mean you have failed financially. It means that your recorded liabilities exceed your assets at that point in time.
If you are in this position, start by understanding which debts carry the highest interest rates, whether you have a basic emergency reserve, and how much you can realistically save each month.
Consider prioritizing expensive debt, making consistent payments, and avoiding new balances you cannot comfortably repay. Continue building savings where practical so an unexpected expense does not automatically become more debt.
Your net worth may take time to improve. What matters is whether your financial choices are helping you move toward greater stability.
Frequently Asked Questions
Is net worth the same as income?
No. Income is money you earn over a period, such as a paycheck or business revenue. Net worth is the value of your assets minus your liabilities at a particular moment.
Someone can earn a high income but have a low or negative net worth if they spend heavily or carry substantial debt.
Should I include my home in my net worth?
For a general household net worth calculation, yes. Include a reasonable estimate of your home’s current market value as an asset and the outstanding mortgage balance as a liability. The difference represents your home equity.
Some specialized financial or legal tests use different rules. For example, the SEC’s accredited-investor net worth test generally excludes the value of a primary residence and applies special rules to related mortgage debt. Do not use an ordinary household net worth calculation as a substitute for a specific eligibility test.
Should I include my 401(k) and IRA?
Yes. Include the current value of your 401(k), traditional IRA, Roth IRA, and other retirement accounts in a general net worth calculation. Remember that taxes, withdrawal restrictions, and potential penalties can affect how much you could actually access.
Can my net worth decrease even if I save money every month?
Yes. Investment losses, falling property values, unexpected expenses, or new debt can outweigh the money you save. Review the reasons for the change before deciding whether your financial plan needs to change.
How much net worth should I have for my age?
There is no single target that applies to everyone. Income, living costs, family responsibilities, debt, and retirement goals vary widely. Instead of relying on a universal number, compare your progress with your own goals and financial circumstances.
What is the difference between net worth and cash flow?
Net worth measures what you own minus what you owe at a specific point in time. Cash flow measures money coming in and going out over a period. Tracking both helps you understand your financial position and whether your day-to-day finances support your long-term goals.
Final Thoughts: Measure Progress, Not Just the Number
Your net worth is a useful financial snapshot, but its real value comes from tracking it consistently and understanding what drives the changes.
An increase may reflect savings, debt reduction, investment gains, or higher property values. A decrease may reflect market losses or unexpected expenses rather than poor financial decisions.
The goal is to build a clearer picture of your financial life so you can make better-informed decisions over time.
Start with your current numbers. Calculate your net worth, save the result, and revisit it next month.
Use the TradeRiskMath Net Worth Calculator to get started, then build a regular habit of reviewing your assets, liabilities, and progress toward your financial goals.
Sources and Further Reading
- Board of Governors of the Federal Reserve System — Results of the 2025 Survey of Consumer Finances (real median family net worth of $215,900 in 2025)
Disclaimer: This article is for educational and informational purposes only. It does not provide individualized financial, investment, tax, or legal advice. Asset values and investment returns can change, and estimates may not reflect the amount you could receive in an actual sale.
1 Comment.